Strictly Private & Confidential
Solar, Without The Wait.
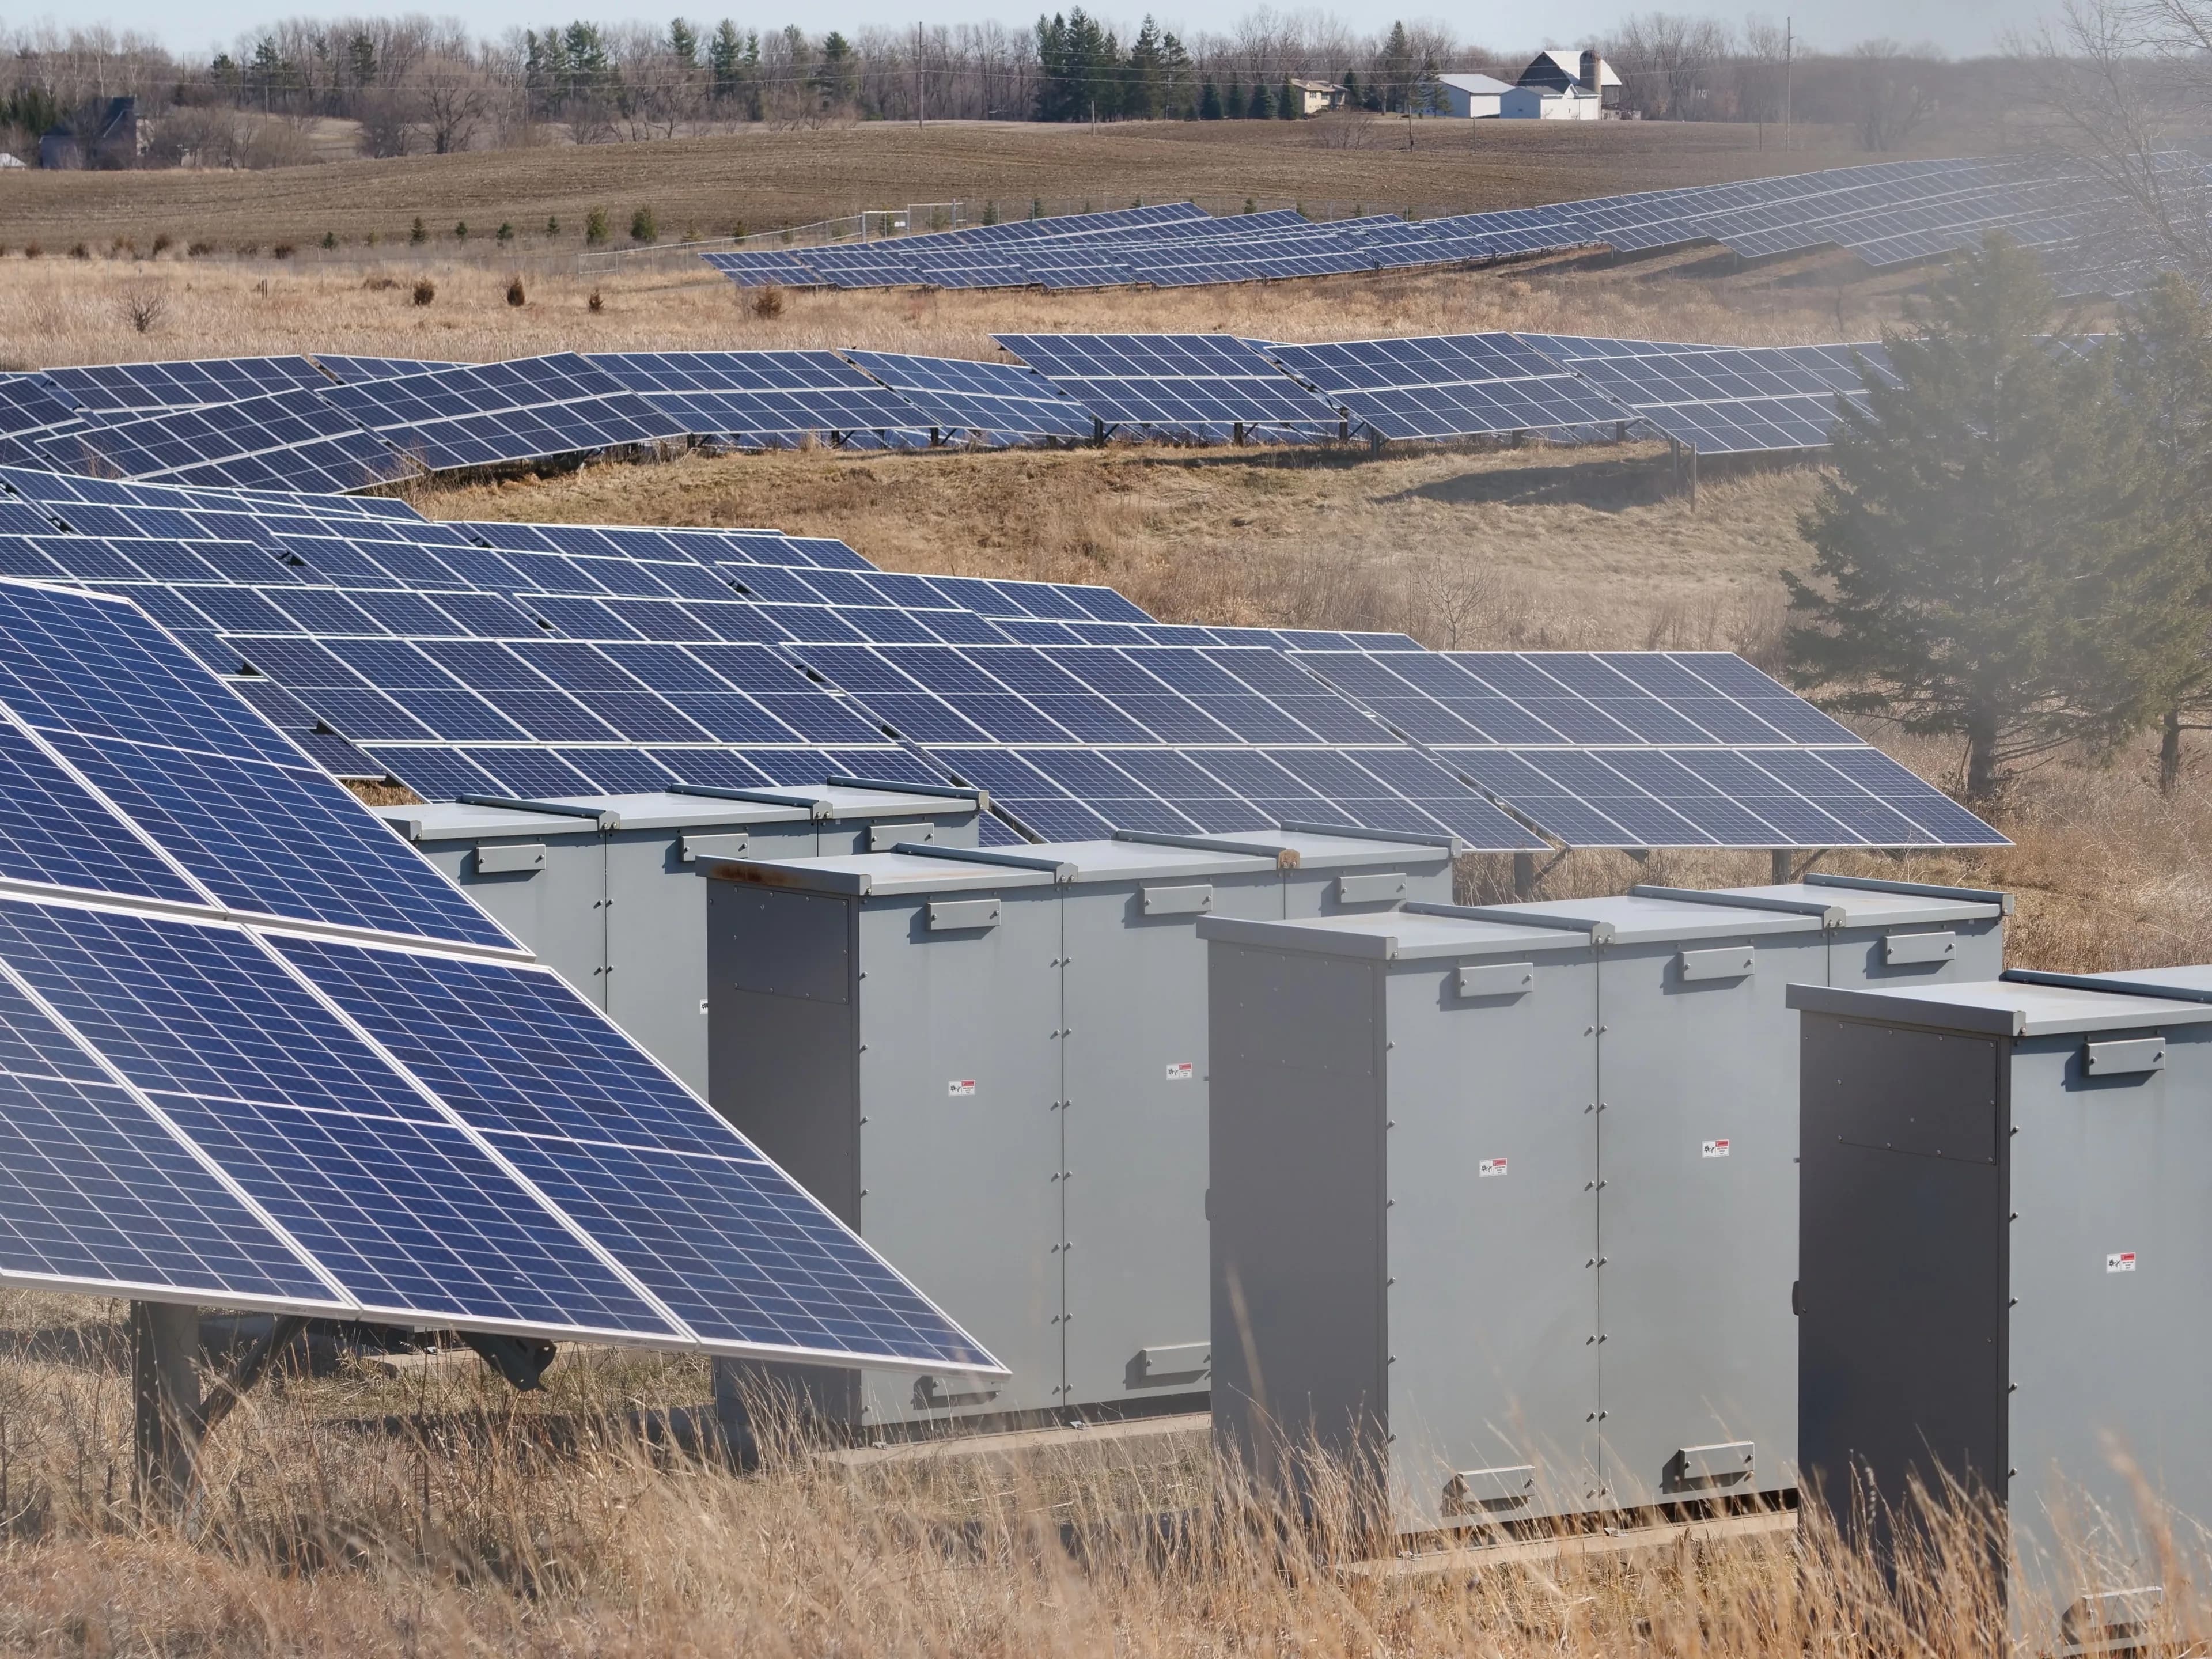
Group-Captive Solar — An Investment Offer. Compressed payback. Zero-capex corporates. Institutional-grade structuring, from land to PPA.
The Problem
Two sides. Two bad options.
The Investor
7–9 yrs
Buys land, builds a solar plant, can't find a buyer for the power — defaults to the state DISCOM feed-in rate. Payback stretches out for years.
The Corporate
No Capex
Pays a premium commercial tariff for grid power. Wants to go captive — but solar capex sits outside the core business budget.
Sinojia Capital exists in the gap between them.
One structure, one negotiated PPA, one dedicated SPV — the investor’s capital and the corporate’s power bill both land in a better place.
The Sinojia Capital Model
One structure. Three winners.
Investors
Capital, priced-in return
AAA Corporates
Offtake, zero capex
EPC Giants
Execution at scale
The Sinojia Capital Role
The EPC partner anchors the project SPV that owns the plant and signs the corporate’s power contract. Sinojia Capital negotiates that relationship — then channels investor capital into the project through its own dedicated investor SPV.
The Return Profile
Same sun. Faster return.
Standalone solar
7–9years to payback
Selling into the grid alone.
Sinojia Capital group-captive
3.5–4years to payback
Corporate offtake, structured.
Equity IRR, base case
13–17%
Indicative capex per MW
₹3–3.5 Cr
Asset / PPA life
25 yrs
The gain comes from where the power is sold, not from taking on more risk. A corporate offtaker's own commercial grid tariff runs well above a DISCOM's feed-in purchase rate for solar power — Sinojia Capital's structuring captures that gap for the investor, without disclosing either party's exact negotiated rate.
Market-benchmark illustration, India group-captive solar, 2026 — not a specific project's modeled return. Can move materially higher where accelerated depreciation applies. Sinojia Capital's negotiated project-level tariff and cash flows are confidential and shared with qualified investors under NDA — not published here.
Capex moves with domestic-content (DCR/ALMM) panel-sourcing mandates and prevailing import duty on solar cells and modules — both set by current government policy and subject to change.
The Structure
Whoever invests, owns the profit.
The corporate offtaker's compliance stake is negotiated deal-by-deal — sometimes funded by the corporate itself, sometimes arranged by Sinojia Capital through an internal book adjustment instead. Either way, it never dilutes investor economics: profit belongs to whoever actually put in the capital.
Step 1
Your Capital
Committed via EOI, called only at deal close.
Step 2
Sinojia Capital's Investor SPV
Pools investor capital, takes a direct stake below.
Step 3
The Project SPV
EPC-anchored. Owns the plant. Holds the PPA.
Sinojia Capital’s Own Stake
No service fees. No upfront charges. Sinojia Capital is paid in equity — a stake in the project itself, sized to the deal and agreed case-by-case — so its own payback depends on the plant developing, deploying, and running smoothly for years. It only earns when the project does.
Regulatory Tailwind — 2026
The Electricity (Amendment) Rules, 2026 widened this further: equity can now be aggregated across a corporate group's own subsidiaries, and a project SPV is formally recognised as its own legal person. Group-captive solar just got easier to structure — not harder.
Structuring approach, confirmed with legal counsel on a per-transaction basis — not a guaranteed statutory outcome.
Where We Build
Wherever you are, we can build there.
Solar Irradiation
Stronger generation potential shortens payback further — but any site with a viable capacity utilisation factor can qualify, anywhere in India.
Open-Access Policy
States offering captive-friendly rules — waived surcharges, low wheeling charges — get evaluated first, wherever they sit on the map.
Land & Grid Access
Available land and a short, affordable grid connection shape the economics of every site we assess.
Corporate Proximity
We build near where you actually draw power — site selection follows your load, not a fixed map.
Sinojia Capital evaluates sites pan-India, not off a shortlist — most major industrial states now offer group-captive-friendly open access policies. India's group-captive solar market is moving at scale: recent project financings across data centers, auto manufacturing and heavy industry have ranged from 12 MW to over 150 MW in a single deal.
How It Works
From EOI to energised SPV.
01
Submit an EOI
A 5–10% token, non-refundable once signed — refunded only if the project doesn't proceed or isn't fully funded by start date.
02
Sinojia Capital pools capital
EOIs are gathered into a dedicated solar allocation until there's enough committed to act.
03
We match the deal
Corporate offtake is negotiated; the EPC partner anchors the project SPV and signs the power contract.
04
SPV invests, capital called
Sinojia Capital's own investor SPV takes its stake. Your capital is called only once the deal is closed.
The Ask
Reserve your place in the sun.
Reserve your position with a 5–10% EOI amount — non-refundable once signed. Refunded only if the project doesn't proceed, or isn't fully funded by its start date; any other refund is at Sinojia Capital's discretion.
Strictly Private & Confidential
Illustrative, market-benchmark figures only — not investment advice or a securities offering. Actual project economics are confidential and shared with qualified investors under NDA.
© 2026 Sinojia Capital Infratech LLP. All rights reserved. This document and its contents are proprietary and confidential, intended solely for the named recipient, and may not be reproduced, distributed or disclosed to any third party without prior written consent.